4 Retirement Income Styles Every Physician Should Know
Key Points:
- There is no one-size-fits-all plan for sustainable retirement spending, yet financial planners may only specialize in one type of retirement income style.
- Four retirement income styles to consider: Total Return, Time Segmentation, Income Protection, or Risk Wrap Strategies.
- It’s okay to have a different retirement income style from that of your spouse, family, and friends.
You know you’re supposed to save and invest for retirement throughout your career. But what are you supposed to do with those savings once you’re near retirement? Most physicians have no idea, and for good reason – creating a sustainable retirement spending plan is far more complicated than saving for retirement. Planning your retirement finances is one of the most common reasons late-career docs will seek a financial planner.
The problem – a financial planning firm may specialize in one retirement strategy for their clients, when there are several to consider, such as investment-based approaches, bucketing approaches, annuity-based approaches. One framework for soon-to-be retirees to evaluate these strategies is the “Retirement Income Style Awareness” or RISA® methodology, a free but proprietary assessment created by Wade Pfau, Ph.D., CFA, RICP and Alex Murguía, Ph.D.
(Important disclaimer: I have no financial relationship with anybody involved with RISA®. This is not an advertisement or endorsement for RISA® or Retirement Researcher, LLC, the firm that Drs. Pfau and Murguía they lead.)
In a nutshell, RISA® focuses on two main themes that can help determine the optimal retirement strategy:
#1 Probability-Based vs. Safety-First Theme:
- How comfortable are you with relying on market returns for the success of your retirement income plan? (Probability-Based)
- How strongly do you feel the need for protected sources of retirement income regardless of how the market performs? (Safety-First)
#2 Optionality vs. Commitment Theme:
- How strongly do you prefer a flexible retirement strategy that you can adjust over time? (Optionality)
- How strongly would you prefer to have a set-it-and-forget-it plan that minimizes the need to constantly revisit your retirement income choices? (Commitment)
RISA® creates a two-by-two matrix based on these two competing themes with four resulting retirement income styles:
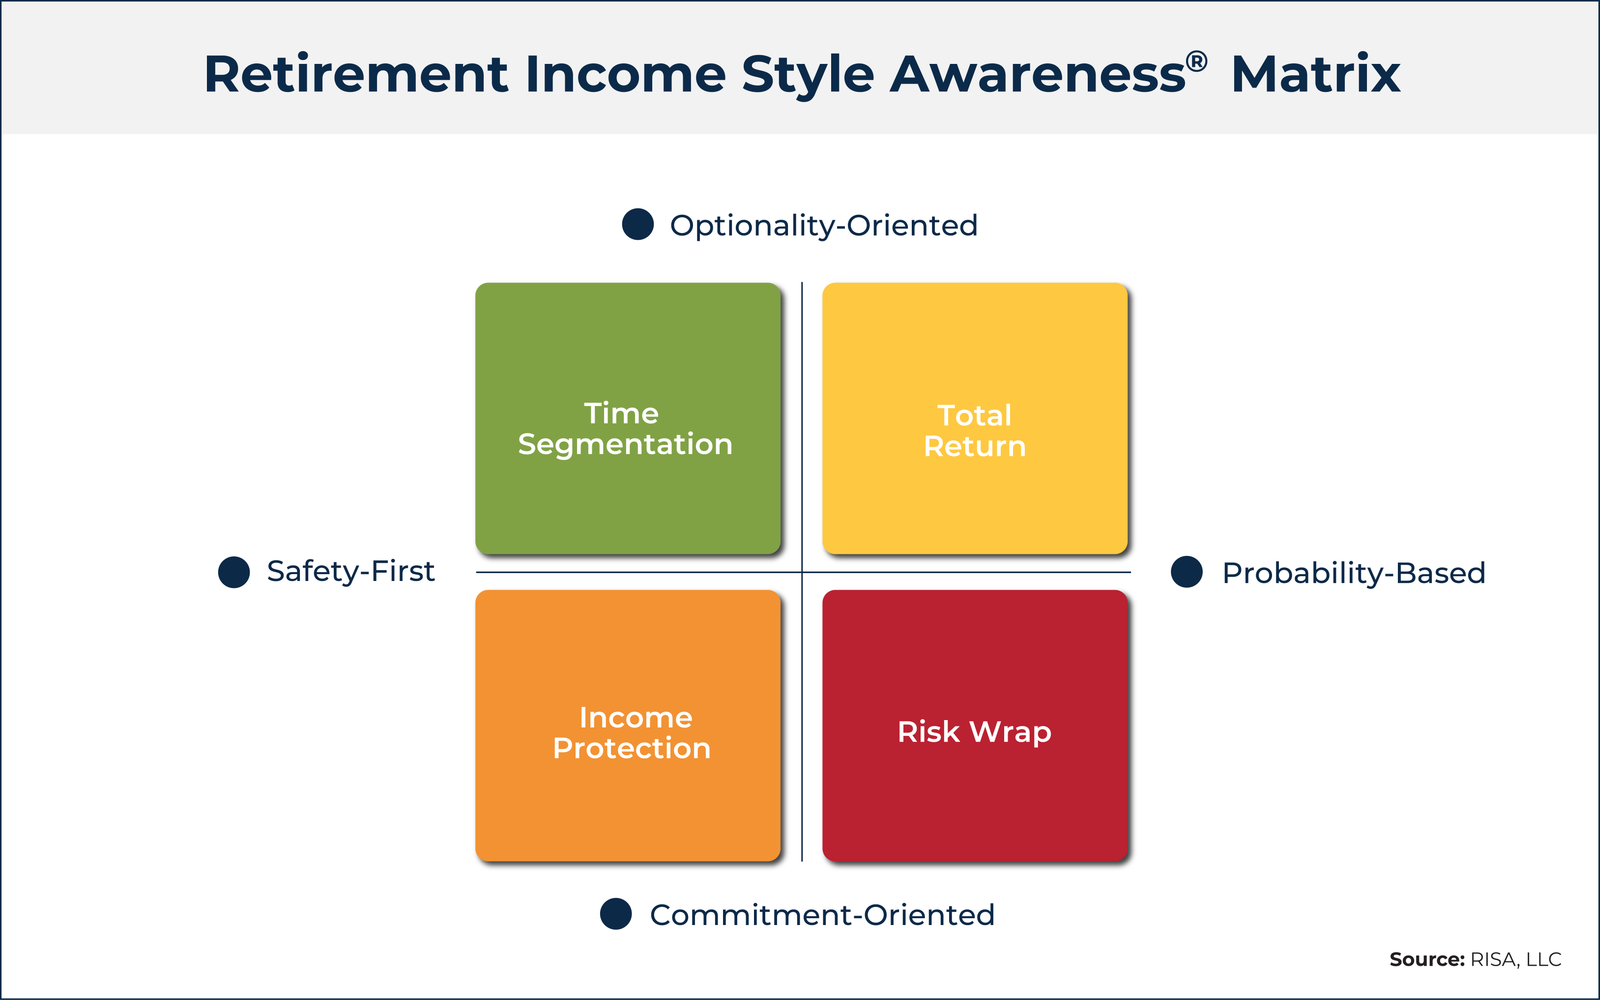
As we go through each of the four retirement income styles, consider which resonates with you the most – it is possible more than one may make sense.
#1) Total Return – Probability-based + Optionality Oriented
The first style mirrors how most of us invest for retirement – using a diversified portfolio of stocks, bonds, and other assets, and developing a systematic and sustainable withdrawal strategy from which to spend in retirement. Total Return is ideal if you can be flexible with your spending (e.g. spend less during down years and loosen the purse strings when your investment portfolio does better than expected).
Significant advantages to this strategy:
- You maintain control of your nest egg.
- If you die prematurely, your heirs will inherit your nest egg, possibly with tax benefits.
- Opportunity to tax-optimize withdrawals between pre-tax, tax-free, and taxable assets.
- Maximizes chance that your investment portfolio may maintain its value or even grow after decades of retirement if the market does well, allowing you to make large donations or bequests at the end of your life.
- Highest chance of beating inflation.
Significant disadvantages to this strategy:
- Requires an interest and understanding of taxes and the market – for some, this could be a dealbreaker.
- A deep and prolonged market downturn can be numerically and psychologically devastating.
- Requires more maintenance and attention due to its complexity.
- Potential estate/inheritance tax issues depending on your state.
Achilles heels:
- Cognitive decline. If you lose the ability to make keep track of your accounts, make critical decisions on your nest egg spending or fall victim to a scam, the results can be devastating.
- Divorce can also be devastating due to potential splitting of assets.
- Death of the more financially attuned spouse.
#2) Time Segmentation – Safety First + Optionality Oriented
Commonly known as “bucketing”, the Time Segmentation strategy involves investing differently based on when the money will be spent. For example, you might organize your investments into a short-term bucket, and intermediate-term bucket, and a long-term bucket. The short-term bucket might contain safe assets like cash or short-term bonds, and the long-term bucket might contain more volatile assets with a higher long-term expected return. The idea is that during down years, you could spend from the short-term bucket, and during up years, you could sell from the long-term bucket to replenish your short- and intermediate-term buckets.
Significant advantages to this strategy:
- Peace of mind from knowing that a near-term fund is always there to ride out any tough times.
- Intuitive and easy to organize mentally.
- Otherwise resembles Total Return.
Significant disadvantages to this strategy:
- Potentially less upside compared to Total Return approach since you may sacrifice portfolio growth to ensure the short-term bucket always stays full.
- Otherwise resembles Total Return.
Achilles Heels:
- Same as Total Return.
#3 Income Protection – Safety-First + Commitment Oriented
In the Income Protection strategy, you use some or all of your nest egg to create a lifelong stream of consistent income like a pension. The simplest example is a single-premium immediate annuity, where you pay a lump sum premium to a life insurance company, and they immediately start paying you a set amount of money per month for the rest of your life based on a set interest rate. Other common examples include a single-premium deferred annuity, where the payout doesn’t start for a set number of years, but the benefit is higher once it begins. Social security retirement benefits are also an example of Income Protection most of us will earn through our working careers.
Significant advantages to this strategy:
- Simple, easy to understand, and requires zero investing knowledge or interest.
- Peace of mind of knowing income will never stop even if you live to 120.
- Many lifelong savers struggle with giving themselves “permission to spend” during retirement – annuities can help these retirees feel comfortable spending or giving more money in retirement.
- If the annuity ends at with your lifetime, there are no estate/inheritance tax issues.
- Eliminates market and cognitive decline risk.
Significant disadvantages to this strategy:
- No protection from inflation. A $150k/year benefit starting today will feel more like $75k/year in 24 years assuming 3% inflation.
- Awful tax treatment at withdrawal.
- If in a retirement plan: All annuity income is taxed as ordinary income, Required Minimum Distribution rules still apply, must be age 59.5 to avoid 10% penalty.
- If not in a retirement plan: All annuity income is taxed as ordinary income, and earnings are taxed first (as opposed to the non-taxable return of your premium).
- Irreversible decision unless you pay hefty surrender charges. Administrative fees, sales charges, and commissions are also included in the premium.
- Once the premium is spent, it is no longer available for heirs or charity.
- Risk of insurance company going out of business and policyholder not made whole by your State (e.g. Executive Life Insurance bankruptcy in 1991).
Achilles heels:
- Health problems or bad luck causing you to die prematurely/unexpectedly. The monthly payments would stop, and the life insurance company would owe you nothing. (Some annuities offer “Joint & Survivor” that pay benefits until the second spouse dies or a guaranteed “term certain” payout period even if you die before that – the tradeoff, however, will be a lower monthly benefit amount).
#4 Risk Wrap – Optionality + Commitment Oriented
In the Risk Wrap strategy, retirees use variable annuities to create guaranteed lifetime income but still benefit from market returns – all in a single product. With variable annuities, you make payments to the insurance company into brokerage-like subaccounts, and you can choose investments within those accounts. If those investments do well, your annuity payment increases; if they don’t, your annuity payment decreases but never below a guaranteed minimum.
Significant advantages to this strategy:
- Provides an all-in-one solution to both investing and guaranteed lifetime income using a single account.
- Potentially higher payments and better protection against inflation compared to a simple annuity.
- Otherwise like Income Protection above.
Significant disadvantages to this strategy:
- Guaranteed minimum payment will be lower than that of a simple annuity.
- Maximum payment will be capped even if the market skyrockets.
- Extremely complicated contracts that often lack transparency, and can have very high administration, investment, and sales charges/fees/commissions that far exceed that of simple annuities.
- Combined disadvantages of both Total Return and Income Protection Strategies.
Achilles Heels:
- Premature death (like Income Protection strategy above).
- Cognitive decline, divorce, or death of the more financially attuned spouse (though the contractual protection may limit the downside compared to a pure Total Return strategy)
How to approach your own retirement income planning
I encourage clients approaching retirement to ask themselves the following questions:
- Which retirement income style(s) resonate with you? I personally gravitate toward Time Segmentation with or without Income Protection; you might be different.
- If you’re married, do you know where your spouse falls on this matrix? An open conversation about retirement income styles can be incredibly helpful, especially if it turns out you and your spouse gravitate toward different styles.
- Would you benefit from working with a financial planning firm? A great firm will help you evaluate all the styles with an open mind and support you with whichever style is right for you and your family (as opposed to a one-size-fits-all firm).
Whatever you decide, remember that the right retirement income plan for you and your family may be different from what your friends, colleagues, or family members are doing. That is totally fine – rather than facing this journey with anxiety or confusion, meet it with an open mind and consider this framework as a starting point to a wonderful retirement.
Sources/recommended reading:
- “How to Retire: 20 Lessons for a Happy, Successful, and Wealthy Retirement” by Christine Benz (Chapter 8 interview with Wade Pfau)
- Kitces.com Blog (by Alex Murguía and Wade Pfau): https://www.kitces.com/blog/risa-framework-retirement-income-planning-client-preferences-total-return-strategy-risk-tolerance/
If you would like to have a conversation about your retirement style and how you might manage the retirement transition, I’d love to chat. Schedule a free discovery call with me here.
DocEmpowered blog posts are never AI-generated.
Stanley Liu, MD, FACC is the Founder and Principal Financial Planner of DocEmpowered, LLC. He is also an independent practicing cardiologist, an award-winning medical educator, and the Advocacy Chair of Maryland’s American College of Cardiology Chapter.
Do you want the power to serve your patients, family, and community on your own terms? If you need an evidence-based financial plan to help make that power a reality, book a free discovery call here.
Get more insights by exploring the DocEmpowered Blog.
Blog feature photo credit: Alexander Lunyov on Unsplash